
TSCM: Inside the Investment Room
DOWNLOAD THE PDFTSCM: Inside the Investment Room is a bulletin offering the Firm’s perspectives on current market developments.
Beyond Market Rotation: AI Financing, Earnings Resilience, and Emerging Growth Opportunities
In this edition of Inside the Investment Room, we examine how AI financing concerns, shifting investor positioning and persistent input-cost pressures are influencing market leadership and investment opportunities across small and mid cap equities.
From the expanding role of advanced semiconductor technologies and biosimilars to resilient regional banks and selective industrial opportunities; the team remains focused on identifying businesses whose underlying fundamentals may be stronger than recent share-price performance suggests.
Executive Summary
Market volatility continues to create opportunities as investor positioning and macroeconomic uncertainty drive sector divergence. While AI financing concerns and rising input costs challenge near-term expectations; underlying fundamentals remain supportive across select semi-conductor, healthcare and financial businesses. The team continues to emphasize valuation discipline, company-specific earnings catalysts, and fundamental research to identify durable growth opportunities amid shifting market conditions.
Sector Perspectives — Takeaways
Technology
AI infrastructure remains a compelling structural growth theme. However, financing concerns, slowing growth indicators, and elevated expectations are driving greater differentiation across the technology ecosystem.
- AI financing under scrutiny: Capital availability, data-center valuations, and potential deceleration in frontier-model growth are raising questions about the pace of future infrastructure investment.
- Semiconductor fundamentals resilient. Committed fab construction, advanced packaging, and process-control demand support equipment suppliers, while resetting expectations may create selective opportunities.
- Optical networking opportunities. Adoption of $1.6T networking and the prospective transition toco-packaged optics could benefit select suppliers, although the timing of broader deployment remains uncertain.
Financials
Regional banks and capital-markets businesses have demonstrated resilience, while insurance pricing and margin trends remain mixed.
- Regional banks remain constructive. Net interest income modestly exceeded expectations, aided by loan repricing and manageable deposit costs; the team discussed potential additional exposure.
- Capital-markets activity holds up. Strong trading results and relatively healthy investment banking pipelines remain supportive despite moderation from earlier highs.
- Insurance trends mixed. Soft-cycle conditions and margin concerns reinforce a selective approach to brokers and underwriting businesses.
Energy
Oil prices remain highly sensitive to geopolitical developments, creating a wide range of potential outcomes for energy-related equities.
- Oil outlook remains uncertain. Developments in the Middle East could meaningfully alter crude prices and sector performance.
- International activity offers potential. Select service providers could benefit from a recovery in Middle East activity, although timing remains uncertain.
- 2027 outlook in focus. Upcoming earnings commentary should clarify the outlook for regional activity and future growth.
Industrials & Infrastructure
Industrial demand remains generally constructive, but rising costs and reduced investor positioning are creating valuation dispersion.
- Demand remains relatively solid. Management commentary has been more resilient than share-price performance, despite fuel, freight, and materials cost pressure.
- Positioning may create opportunities. Sector underperformance and reduced investor exposure could support a rebound if earnings and demand stabilize.
- Pricing power remains essential. The ability to offset cost inflation and preserve margins remains central to company selection.
Consumer
Recent gains in staples and retail appear driven more by positioning than by a broad improvement in fundamentals.
- Rotation outpaces fundamentals. Recent share-price strength requires confirmation from upcoming bearnings and demand trends.
- Input costs challenge profitability. Elevated freight, materials, and tariff-related costs may prompt further pricing actions.
- Unit growth under pressure. Higher financing and build-out costs could constrain expansion economics into 2027. AI-enabled travel distribution is also emerging as a longer-term theme.
Health Care
Healthcare performance remains influenced by subsector rotation, with opportunities requiring careful assessment of valuation and company-specific catalysts.
- Medtech valuations attractive. Select businesses appear inexpensive, although the timing of sustained multiple expansion is uncertain.
- Biosimilar opportunity develops. Upcoming patent expirations may benefit pharmaceutical packaging and distribution businesses as manufacturers become more multi-sourced.
- Biotech selectivity critical. Mixed market reactions to clinical news underscore the value of differentiated precision-oncology and longer-acting immunology programs.
Key Macro Trends
- Market Rotation & Positioning: Recent sector leadership shifts appear driven in part by investor flows rather than broad fundamental improvement.
- AI Financing & Infrastructure: Funding uncertainty is weighing on some data-center operators, while committed fab investment and optical networking demand remain supportive.
- Earnings Season as a Catalyst: Upcoming results will help establish whether resilient demand can offset cost pressure and support valuations.
- Persistent Cost Pressures: Fuel, freight, tariffs, and raw materials continue to challenge margins across multiple industries.
- Geopolitical & Commodity Uncertainty: Middle East developments create a wide range of possible oil-price and energy-equity outcomes.
The Bottom Line
The investment landscape remains characterized by divergence between market sentiment and underlying business fundamentals. Although AI financing concerns, geopolitical uncertainty, and input-cost pressures create near-term challenges, select opportunities in semiconductor infrastructure, healthcare, regional banks, and industrials merit continued attention. The team remains focused on valuation discipline, earnings execution, and company-specific catalysts to identify high-quality small and mid cap businesses with durable growth potential.
Disclosures
The views expressed are those of the investment team as of October 2026 and are subject to change without notice. The discussion reflects current opinions and market observations and should not be regarded as investment advice or are commendation regarding any security, sector, or investment strategy. There is no assurance that any forecast, outlook, or investment objective will be achieved.
This does not constitute advice or a recommendation or offer to sell or a solicitation to deal in any security or financial product. It is provided for information purposes only and on the understanding that the recipient has sufficient knowledge and experience to be able to understand and make their own evaluation of the proposals and services described herein, any risks associated there with and any related legal, tax, accounting or other material considerations.
Except where otherwise indicated, the information contained in this presentation is based on matters as they exist as of the date of preparation of such material and not asof the date of distribution or any future date. Recipients should not rely on this material in making any future investment decision.
Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein maybe relied upon as a guarantee, promise, assurance or a representation as to the future.
TimesSquare Capital Management, LLC (“TimesSquare”) is an investment adviser registered with the U.S. Securities and Exchange Commission and is majority owned by Affiliated Managers Group, Inc. It claims compliance with the Global Investment Performance Standards (GIPS®) and is independently verified. A firm that claims compliance with the GIPS standards must establish policies and procedures for complying with all the applicable requirements of the GIPS standards. Verification provides assurance on whether the firm's policies and procedures related to composite and pooled fund maintenance, as well as the calculation, presentation, and distribution of performance, have been designed in compliance with the GIPS standards and have been implemented on a firm-wide basis. Policies for valuing investments, calculating performance, and preparing GIPS Reports are available upon request. GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality content contained herein.
The opinions and information expressed and provided are for general information only and are not intended to provide specific advice or recommendations but rather, a basis from which strategies can be built, taking into account the specific objectives of each portfolio, in terms of return, time horizon, and risk constraints, as well as diverging investment perspectives and assumptions. All material has been obtained from sources believed to be reliable, but its accuracy and completeness are not guaranteed.
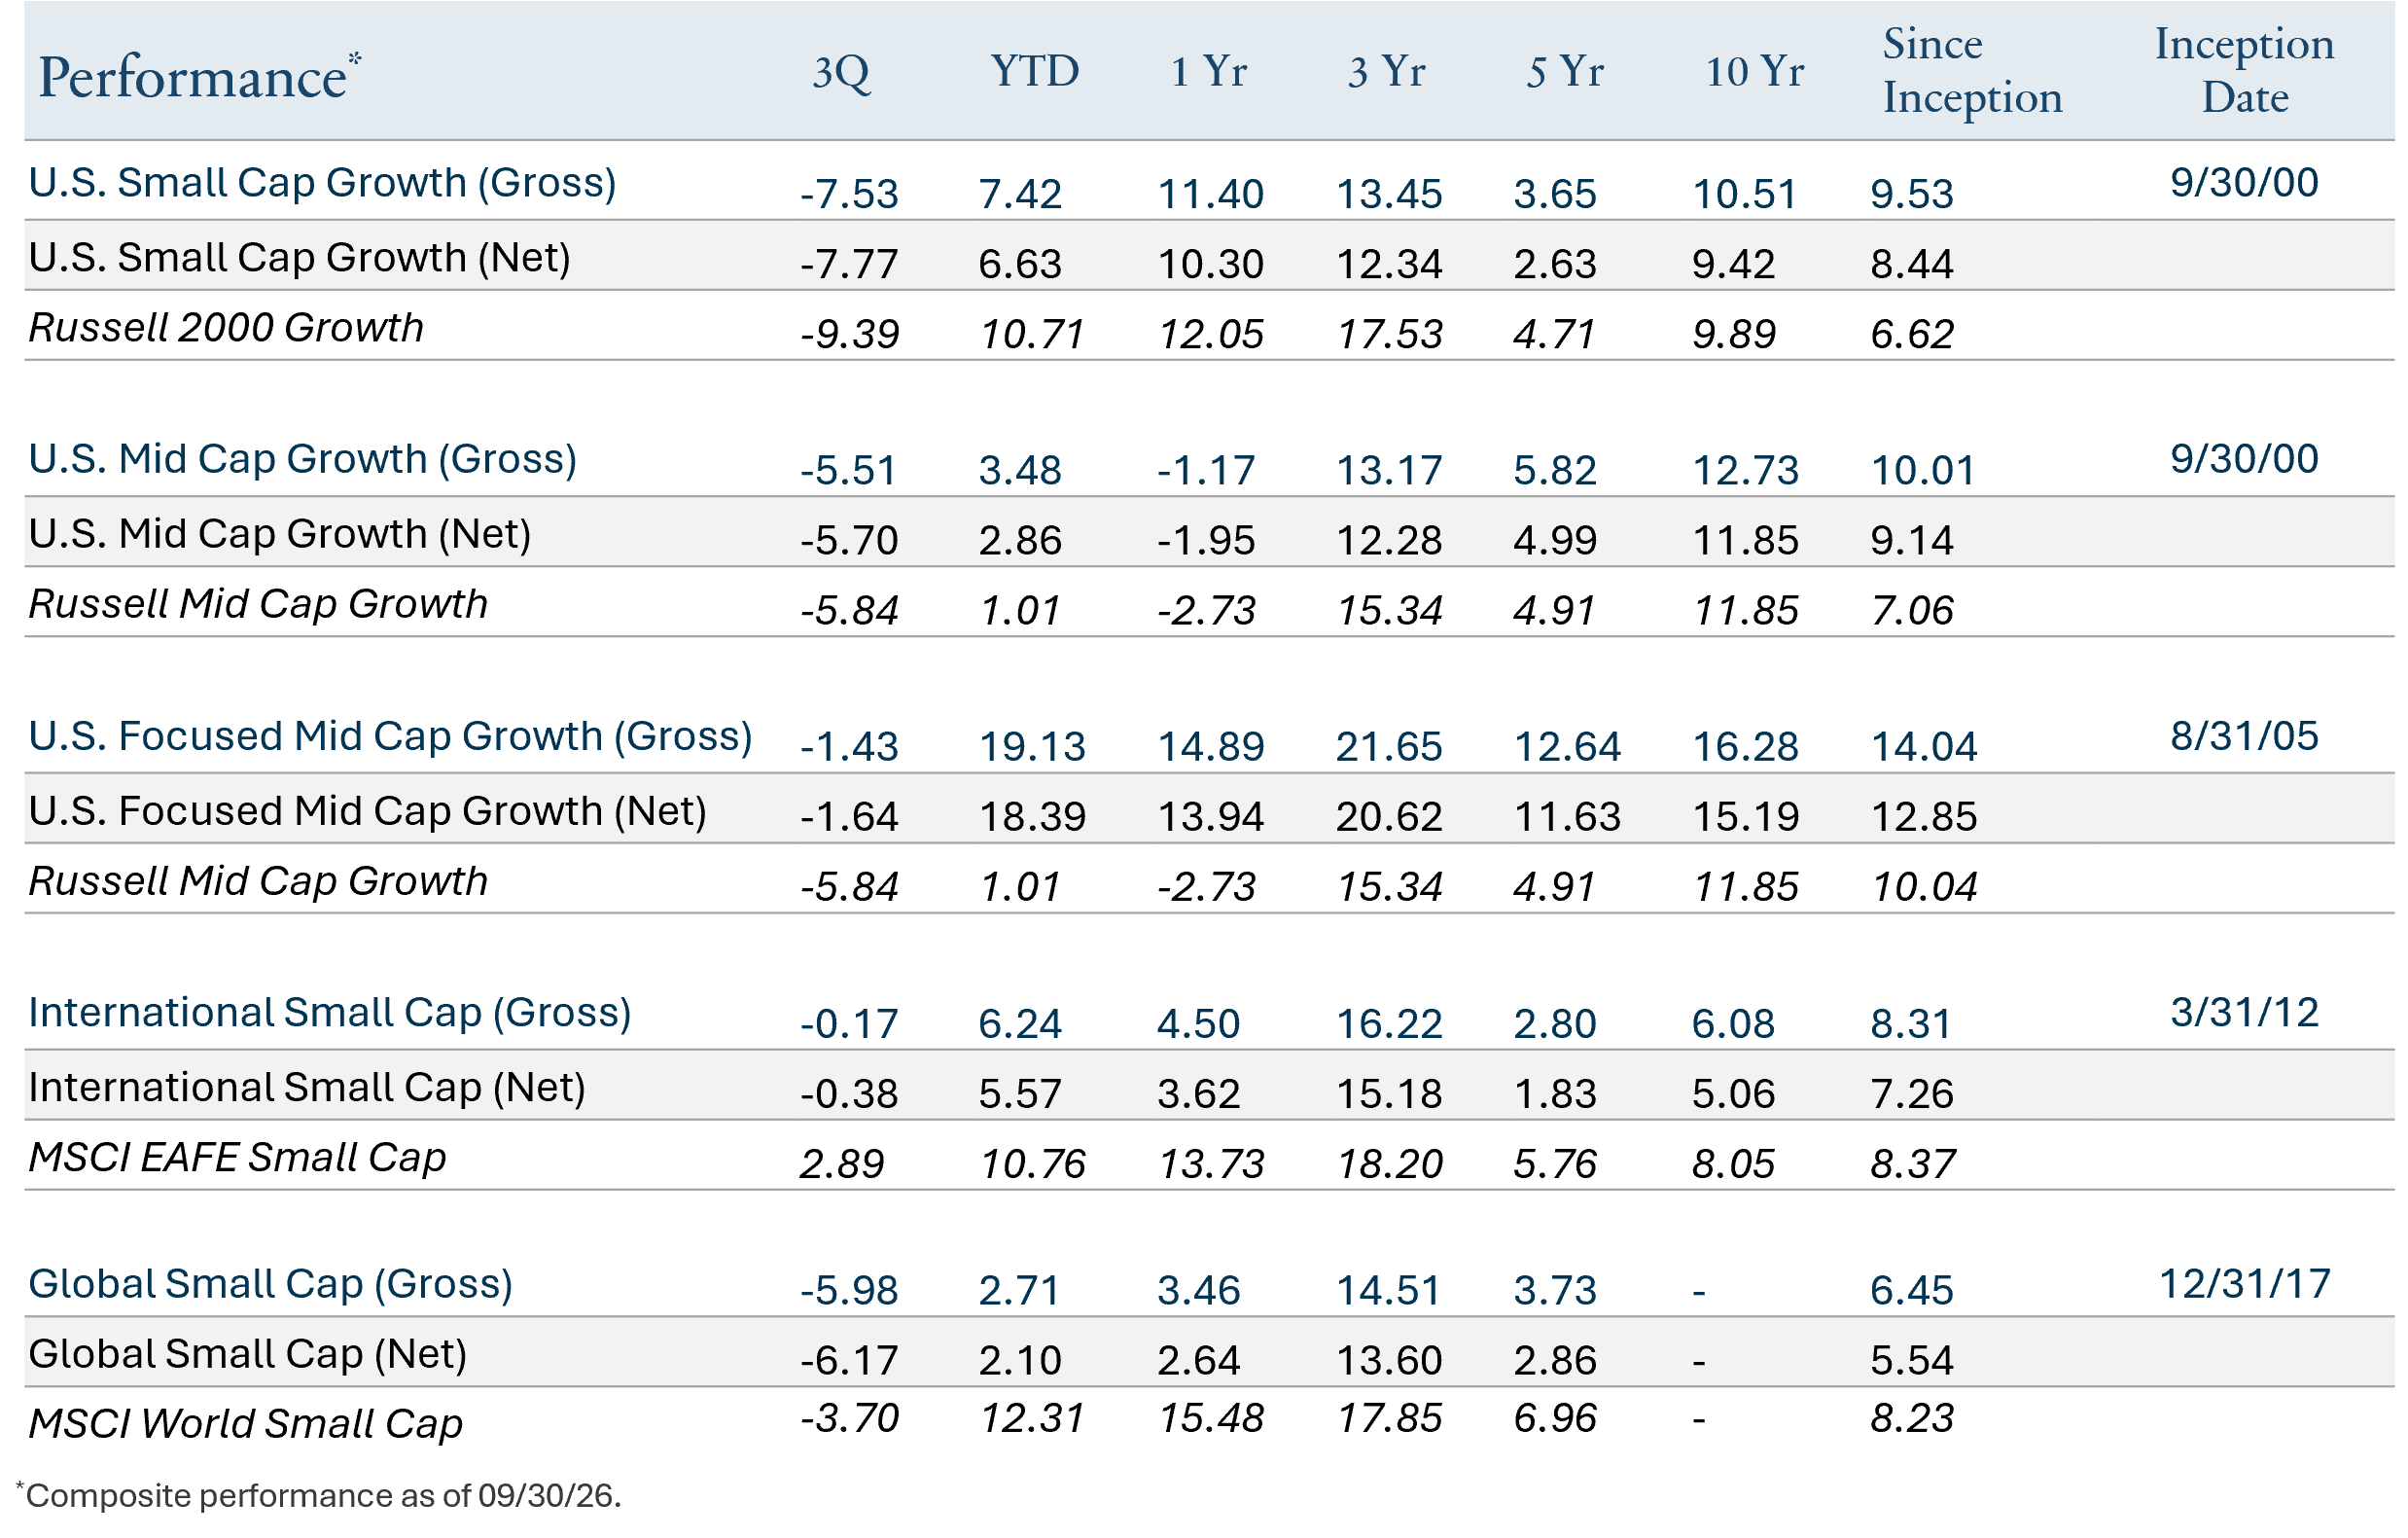
U.S. Small Cap Growth: Performance is measured against the Russell 2000® Growth – a market capitalization-weighted index that measures the performance of those Russell 2000® companies with higher price-to-book ratios and higher forecasted growth rates. All indexes, including the Russell 2000® Growth Index, are based on gross-of-fee returns. FTSE Russell is the source and owner of the Russell Index data contained or reflected in this material and all trademarks and copyrights related thereto. Benchmark returns are not covered by the report of independent verifiers.
U.S. Mid Cap Growth: Performance is measured against the Russell Midcap® Growth – a market capitalization-weighted index that measures the performance of those Russell Midcap® companies with higher price-to-book ratios and higher forecasted growth rates. All indexes, including the Russell Midcap® Growth Index, are based on gross-of-fee returns. FTSE Russell is the source and owner of the Russell Index data contained or reflected in this material and all trademarks and copyrights related thereto.
U.S. Focused Mid Cap Growth: Performance is measured against the Russell Midcap® Growth – a market capitalization-weighted index that measures the performance of those Russell Midcap® companies with higher price-to-book ratios and higher forecasted growth rates. All indexes, including the Russell Midcap® Growth Index, are based on gross-of-fee returns. FTSE Russell is the source and owner of the Russell Index data contained or reflected in this material and all trademarks and copyrights related thereto.
International Small Cap: Performance is measured against the MSCI EAFE Small Cap (Net) Index. MSCI EAFE Small Cap (Net) Index is a trade or service mark of MSCI Inc. The MSCI EAFE Small Cap (Net) Index is an unmanaged, market-weighted index of small companies in developed markets, excluding the U.S. and Canada. Its returns include net reinvested dividends but, unlike the Composite returns shown, do not reflect the payment of sales commissions or other expenses incurred in the purchase or sale of the securities included in the Index. All indexes, including the MSCI EAFE Small Cap (Net) Index, are based on gross-of-fee returns, including net reinvested dividends.
Global Small Cap: Performance is measured against the MSCI World Small Cap (Net) Index. MSCI World Small Cap (Net) Index is a trade or service mark of MSCI Inc. The MSCI World Small Cap (Net) Index is an unmanaged, market-weighted index of small companies in developed markets. Its returns include net reinvested dividends but, unlike the Composite returns shown, do not reflect the payment of sales commissions or other expenses incurred in the purchase or sale of the securities included in the Index. All indexes, including the MSCI World Small Cap (Net) Index, are based on gross-of-fee returns, including net reinvested dividends.
Indices are unmanaged, are unable for direct investment and do not reflect the deduction of fees and expenses.
Past performance does not guarantee future results. There is risk that invested capital may be lost.
